Cheapest Car Insurance in South Africa (2026): What Real Customers Say About Price
No insurer is cheapest for everyone. Here's what customers say about price, renewals and excess, and which insurers also pay claims well.
 By Hellopeter Editorial Team
Cheapest Car Insurance in South Africa (2026): What Real Customers Say About Price
The cheapest car insurance in South Africa is different for every driver. Your premium depends on your car, your age, where the car sleeps at night and your claims record, so the insurer that quotes your neighbour the lowest price may not quote you the lowest. What no quote can tell you is what happens after you sign: whether the price stays fair at renewal, the excess matches what you were told, and the insurer pays when you claim.
That's what real customers tell us in their reviews. This guide shows which car insurers South Africans rate best on price, set against how the same insurers handle claims, based on Hellopeter's AI analysis of customer feedback. Then it walks you through getting a lower premium without buying cover you'll regret.
Which Car Insurers Customers Rate Best on Price
The table shows the eight car insurers with the highest customer ratings for price and excess. That score covers everything customers say about cost after they sign: premiums, renewal increases, excess, refunds and cashback. Next to it is each insurer's claims score, because a low price only helps if the claim gets paid.
| Insurer | Price & excess | Claims handling | What customers say |
|---|---|---|---|
| Prime South Africa | 4.6/ 5 (Excellent) | 4.0/ 5 (Great) | Premiums held for two years; excess reduces to zero |
| King Price Insurance | 4.2/ 5 (Great) | 4.0/ 5 (Great) | One review call often cuts the premium |
| OUTsurance | 4.1/ 5 (Great) | 4.3/ 5 (Great) | Big savings on switching; OUTbonus cashback arrives |
| Old Mutual Insure | 4.1/ 5 (Great) | 3.3/ 5 (Average) | Retention team beats competitor quotes |
| Momentum Insure | 3.9/ 5 (Great) | 2.9/ 5 (Average) | A review call often cuts the renewal increase |
| 1st for Women | 3.9/ 5 (Great) | 2.5/ 5 (Average) | Premiums lowered on request, benefits kept |
| Budget Insurance | 3.8/ 5 (Great) | 2.8/ 5 (Average) | Review calls cut premiums; claim-free cashback paid |
| Santam | 3.8/ 5 (Great) | 3.3/ 5 (Average) | Consultants negotiate lower premiums and excess |
Source: Hellopeter's AI analysis of customer feedback (car insurance averages, price 3.1 and claims 2.9) — September 2026
MiWay, Dialdirect, dotsure and Auto & General come next, all at 3.7 on price. The car insurance average is 3.1, so every insurer in the table sits well above it. Prime South Africa stands out: customers describe premiums held fixed for two years, an excess that reduces month by month, and reviews granted on request when money gets tight.
Cheap Only Counts If They Pay
Price is only half the story. The same reviews show how each insurer behaves at claim time, and the two don't always line up.
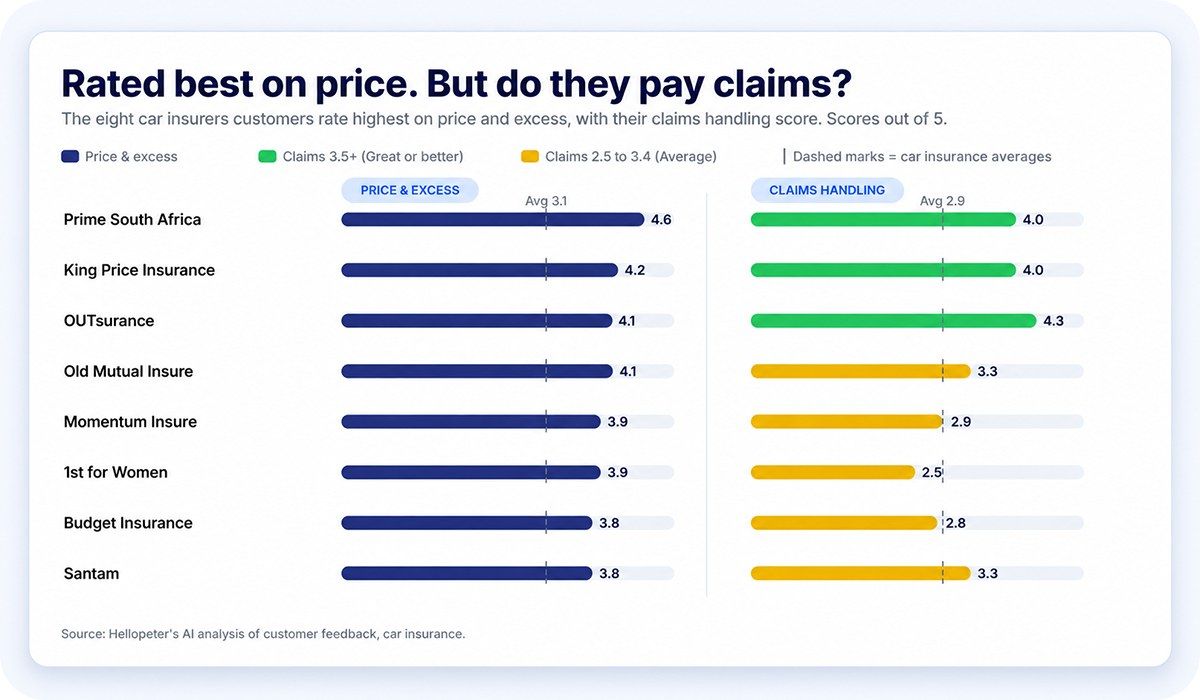
Prime South Africa, King Price and OUTsurance are the only insurers in the table rated “Great” or better on both price and claims. OUTsurance has the strongest claims score of the eight, at 4.3, with customers describing motor claims settled within days and named claims advisors who take ownership. For a closer look, see what South Africans say about OUTsurance.
For Momentum Insure, Budget Insurance and 1st for Women, the picture splits. Customers rate them well on price, but claims handling sits at or below the car insurance average of 2.9. The complaints centre on claims turned down on wear and tear or technicalities, third-party excess that takes months to recover, and claims that sit for weeks without an update.
It works the other way too. Naked Insurance is rated Average on price, at 3.3, yet ties with OUTsurance for the best claims score, at 4.3. Many Naked customers say their premium started lower than rival quotes; the complaints that pull its price score down are about later increases in the premium and excess. A low quote and a fair price over the life of a policy aren't the same thing.
What Pushes the Price Up After You Sign
Across car insurers, the same four complaints drag price ratings down. Knowing them tells you which questions to ask before you sign:
- Renewal increases with little warning. Customers describe steep annual increases they only noticed on a bank statement or in the app, even after years without a claim.
- Excess you only discover at claim time. Higher excess amounts, and extra excesses for things like a single-vehicle accident or a new policy, come as a shock when the claim is lodged.
- Debit orders that don't stop. Premiums taken after a cancellation, on the wrong date or twice in a month, with refunds that take months to arrive.
- Rewards that never arrive. Cashback, referral and voucher promises that customers say weren't paid, or driving-app rewards lost because the app didn't record their trips.
The One Call That Saves the Most
The strongest positive pattern is simple. At insurer after insurer, customers describe calling to review their policy at renewal and saving hundreds of rand a month in a single call, often with a lower excess and the same cover. Retention teams at King Price, Budget Insurance, Dialdirect and Auto & General are praised for exactly this.
So never accept a renewal increase without calling first. And if you're offered a lower premium, check that the cover and the excess haven't quietly changed with it.
How to Find Cheap Car Insurance You Won't Regret
- Compare at least three car insurance quotes like for like. Same car value, same excess, same extras, same drivers. A cheaper quote with a higher excess isn't really cheaper.
- Ask for every excess in writing. Not just the basic excess, but any extra excess for a single-vehicle accident, a driver who isn't listed, or the first months of a new policy.
- Ask what the premium will do over time. Is it fixed for a period? Does it decrease? Does the excess reduce? What exactly must you do to earn the cashback?
- Check the claims score, not just the price. Look up the insurer's Hellopeter profile and read what customers say about claims.
- Tell the full truth on your application. The regular driver, where the car sleeps, modifications and past claims. Customers whose claims were turned down often mention misrepresentation or a driver who wasn't on the policy, and a slightly cheaper premium isn't worth a rejected claim.
- Diarise your renewal date. Call before you accept any increase, and ask for a review.
- Cancel properly if you switch. Cancel in writing, keep the reference number and watch your bank statement. If a premium is taken after you've cancelled, ask the insurer for a refund and ask your bank about disputing the debit.
Other Ways to Pay Less for the Same Protection
- Match the cover to the car. For an older car, third-party, fire and theft cover costs less than comprehensive cover. Our guide to the best car insurance in South Africa explains the difference.
- Declare your tracker. Customers of several insurers report a lower premium or excess once their tracker certificate was loaded.
- Bundle your cover. Multi-car and multi-policy discounts come up again and again in positive reviews.
- Drive less, if you can. Some insurers reward low mileage, but check how the reward is measured and paid before you count on it.
- Choose your voluntary excess with care. A higher excess lowers the premium, but you pay more when you claim.
If Your Insurer Won't Budge
If a renewal increase, a refund or a claim goes against you, put your complaint to the insurer in writing and ask for a reference number. If that doesn't resolve it, you can escalate for free to the National Financial Ombud Scheme, which handles short-term insurance complaints. Our guide to escalating to an ombudsman explains when and how. Sharing your experience on the insurer's Hellopeter profile helps too, because the insurer can reply in public and the next driver gets a fair picture.
How We Compared Car Insurers
The scores come from Hellopeter's AI analysis of customer reviews, the same scores you'll find on our car insurance page. The price and excess score reflects what customers describe about premiums, renewal increases, excess, refunds and rewards. It isn't a quote, and it doesn't compare premiums. Each insurer's scores draw on its short-term insurance reviews, so car, home and other cover are read together. We refresh the analysis every quarter, and the table shows the date the scores were last checked. For more ways to compare before you buy, see our buyer's guides.
A Note on This Article
Hellopeter is independent and impartial. We aren't affiliated with the insurers mentioned, and nothing in this guide is sponsored. The scores are based on public, verified customer reviews on Hellopeter, which change as new reviews come in, so they reflect the picture at the time of publication. This is general information to help you compare, not financial advice, so get your own quotes and read the policy wording before you decide.
Frequently asked questions
- Which Is the Cheapest Car Insurance in South Africa?
- It depends on you. Premiums are priced on your car, your age, your driving record and where you live, so compare at least three quotes like for like. On price and excess, Hellopeter's AI analysis of customer reviews rates Prime South Africa highest, followed by King Price, OUTsurance and Old Mutual Insure.
- How Can I Lower My Car Insurance Premium?
- Call your insurer before you accept a renewal and ask for a review. Customers regularly describe saving hundreds of rand a month in one call. A tracker, multi-car or multi-policy discounts, lower mileage and a higher voluntary excess can also bring the premium down, but check the cover hasn't changed.
- Why Did My Car Insurance Go Up at Renewal?
- Premiums are reviewed every year, and many customers say steep increases arrive with little warning, even after claim-free years. Ask the insurer to explain the increase in writing, request a policy review, and compare quotes elsewhere before you accept it. A single call often brings the premium down.
- Is the Cheapest Car Insurance Worth It?
- Only if it pays when you claim. In Hellopeter's analysis, some insurers that customers rate well on price score at or below average on claims handling. Compare the claims score alongside the price, ask for every excess in writing, and read what customers say about claims before you switch.
- What Do Customers Complain About Most Regarding Car Insurance Prices?
- The most common complaints are renewal increases that arrive with little warning, excess amounts discovered only at claim time, debit orders that continue after cancelling, slow refunds, and cashback or referral rewards that weren't paid. Asking the right questions before you sign avoids most of them.